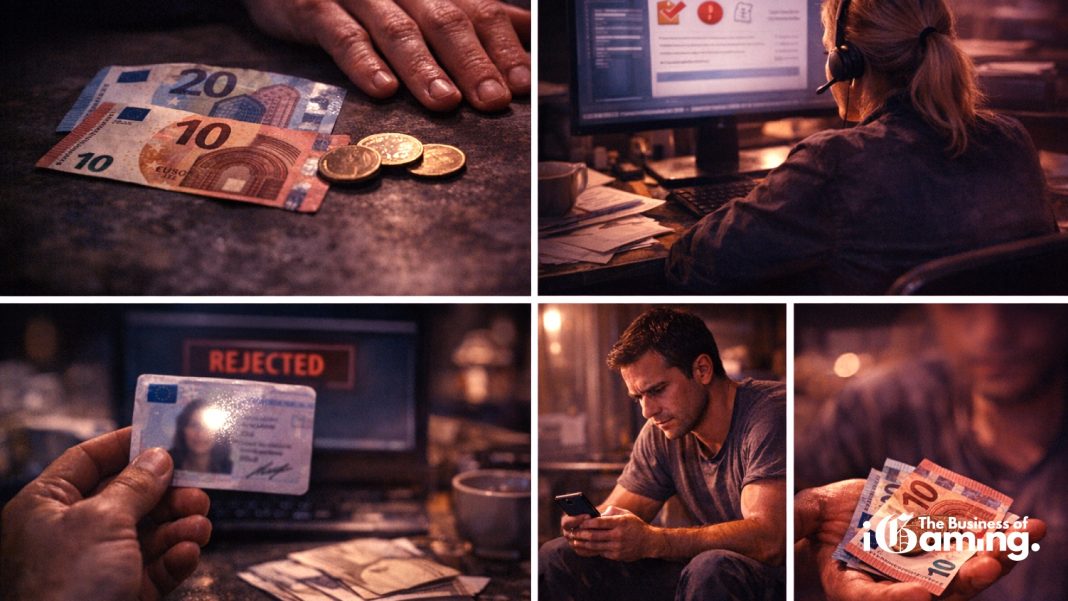
Every operator has a version of this story. A player wins a modest amount, maybe €40, and asks for it back. The request lands in a manual review queue on Friday afternoon. Compliance flags the account for a fresh identity check because the document on file is eleven months old. The player uploads a photo of a driving licence, gets an automated rejection for glare, tries again on Saturday, hears nothing until Monday, and finally receives the money on Tuesday.
The €40 arrives. The player never deposits again.
That is withdrawal friction player value in one paragraph. The payout was tiny. The cost was a customer who might have been worth ten times that over the following year. And almost nobody inside the business saw it happen, because the teams that caused the delay and the teams that measure lifetime value are looking at different dashboards.
Why the small payout is the dangerous one
Large withdrawals get attention. They trigger enhanced due diligence, senior sign-off and sometimes a phone call. Everyone understands that a five-figure cashout needs care, and most players who win that much expect a wait.
Small withdrawals are different. They are frequent, low-risk and emotionally loaded. A player who has just won €40 is at the peak of their goodwill towards your brand. That is exactly the moment the experience should be effortless. Instead, it is often the moment the operator introduces the most friction, because the same review rules apply regardless of amount.
The result is a strange inversion. The player who could do the most long-term damage to your reputation, the recreational one who talks to friends and leaves reviews, gets the same treatment as the account that looks like a laundering risk.
The three sources of withdrawal friction
KYC re-checks at the wrong moment
Periodic re-verification is a legitimate compliance requirement in most regulated markets. The question is not whether to do it, but when. Triggering a document refresh at the point of withdrawal turns a routine hygiene task into a hostage situation from the player’s perspective. They cannot see the compliance logic. They see a company that took their money instantly and now wants paperwork before returning it.
Operators that run re-verification proactively, prompted during a quiet login rather than at cashout, tend to hear far fewer accusations of stalling. The check is the same. The timing is not.
Manual review queues with no service level
Many payment operations teams have a manual queue for anything that fails an automated rule. What they often lack is a published internal target for how long an item can sit there. Without a service level, the queue grows on Fridays and shrinks on Mondays, and the player experience swings with staffing rather than risk.
Weekend and banking cut-offs
Some delay is outside the operator’s control. Bank transfers do not settle on Sundays in most markets. But the operator controls how that is communicated. “Pending” with no explanation reads as suspicion. “Approved, your bank will credit this on Monday” reads as competence. The elapsed time is identical.
Why finance and compliance never see the same numbers
Here is the structural problem. Compliance measures its own success by cases reviewed, false negatives avoided and regulatory findings closed. Finance measures cash out the door and processing costs. Marketing and CRM measure retention and player lifetime value.
None of those functions owns the number that matters here: the retention rate of players in the thirty days after their first withdrawal, split by how long that withdrawal took.
If you have never run that report, it is worth doing before reading further. In our experience talking to operators, the pattern is rarely subtle. Players whose first cashout was fast tend to keep playing. Players whose first cashout dragged tend to disappear. The correlation does not prove causation on its own, but it is strong enough that ignoring it is a choice.
What “good” looks like in practice
Fixing withdrawal friction player value loss does not require rewriting your compliance policy. It requires a few operational decisions that cut across departments.
- Tier the review rules by amount and risk score. A €40 payout to a verified, low-risk account with a clean deposit history should not sit in the same queue as a €4,000 payout to a two-day-old account.
- Move re-verification away from the cashout moment. Prompt for refreshed documents during normal sessions, well before any expiry date, and make the upload work on a phone camera the first time.
- Set and monitor an internal service level for manual review. Hours, not days. Report it weekly alongside retention, not in a separate compliance pack.
- Be specific in status messaging. Tell the player what stage the request is at and what happens next. Silence is what turns a delay into a grievance.
- Give one person the number. Someone, whether in product, operations or finance, needs to own post-withdrawal retention as a KPI. Until then, it belongs to nobody.
The affiliate angle
Affiliates feel this problem before operators do. A player who has a bad cashout experience does not usually complain to the casino. They complain in the comments section of the review site that sent them there, or in a Trustpilot post that the affiliate then has to decide whether to address.
Operators that want affiliates to keep sending quality traffic would do well to share their withdrawal performance, at least in broad terms. A brand that can say most standard payouts clear within a working day has a selling point that no welcome bonus can match.
Small money, big signal
The €40 withdrawal is not a finance problem. It is a trust test that the player is running on your business, usually without realising it. Pass it and you have a customer who believes you will pay. Fail it and no amount of retention marketing will bring them back.
If you work in payments, compliance or CRM and have never sat in the same meeting to look at post-withdrawal churn, that meeting is the cheapest fix available to you. Book it. Then tell us what you found, because Business of iGaming would like to hear how the numbers look from inside your operation.